Do Adult AI App Payments Require ID? A Founder's Guide
Adult AI payment verification: separate buyer ID, card checks and age assurance. Use practical checkout messages to reduce confusion without evading checks.
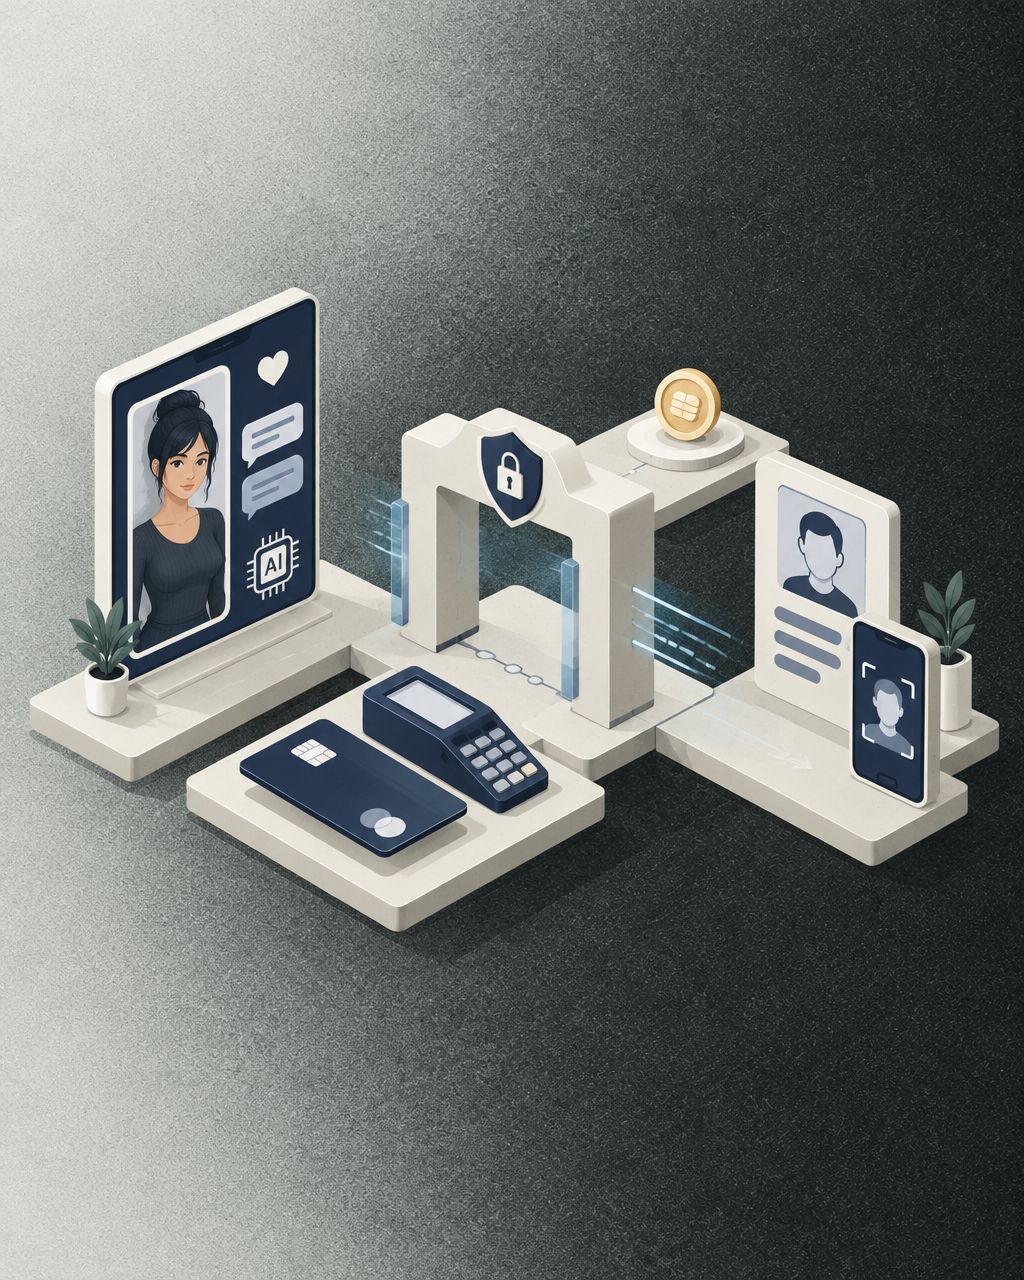
Some adult AI app payments require buyer identity checks, and others do not; the card provider decides what is required for the transaction. Merchant onboarding, card authentication and age assurance for adult content are separate checks, so an easy merchant signup does not guarantee an ID-free buyer checkout or legally sufficient age verification.
For founders choosing checkout for adult AI apps, buyer completion deserves its own investigation. A provider can fit your business and still introduce a payment journey customers do not understand.
Do adult AI app payments require ID?
There is no universal yes-or-no rule for every adult AI transaction. The answer depends on the payment arrangement, provider requirements and applicable law. In Railbed's card flow, the provider collects card details on its own page and decides which identity checks to require.
The buyer does not need to supply a crypto wallet for that card purchase. The merchant receives USDC settlement. These facts do not imply anonymous payment: the card provider can still require personal information or verification.
| Check | Who or what it concerns | What it establishes | What it does not establish |
|---|---|---|---|
| Merchant onboarding | The business and its operators | The business has met that arrangement's onboarding requirements | Every buyer will avoid checks |
| Buyer identity verification | The person using the payment service | Identity evidence has met the provider's requirements | The app has met every adult-content access duty |
| Card authentication | Authorization of the card transaction | A bank or payment process has authenticated the payment | Universal proof of age |
| Content age assurance | Access to adult material | Whether the chosen process meets the applicable access standard | The card transaction will be approved |
| App account verification | Ownership of the game or app account | Which account should receive access | Payment itself has completed |
A buyer identity check establishes identity to the provider's required standard, not every fact about that person. A card challenge establishes a different fact: whether the payment can be authenticated. Neither should be silently recorded in your app as legally verified age.
Do not use one check's success as evidence that all the others are satisfied. That mistake creates misleading checkout claims and gaps in product controls.
Why this matters commercially
A customer arriving from your app expects to buy access or credits. If checkout unexpectedly asks them to interact with another company, provide identity information or return through a second tab, the customer needs an explanation.
That is not evidence that all verification is bad. Required checks must remain in place. The product problem is unnecessary uncertainty: the customer does not know who is asking, why the step exists or whether the purchase succeeded.
In 2026, assess completion through the entire journey. A high click rate on Buy credits does not prove customers can complete the provider flow, and a paid transaction does not prove your app delivered the purchase.
How Railbed's provider routing works
The published buyer guide says Smart Routing considers the buyer's country, checkout currency, amount, provider minimums and current availability. It filters eligible methods and ranks the choices.
Depending on the checkout configuration, the buyer can go directly to the top choice, see a provider list or be sent to a selected provider. The card provider then shows its terms and collects the card payment. The original checkout waits for verified confirmation.
There are three important limits:
- Best match is a recommendation, not an approval guarantee. A card can still be declined.
- Identity checks are the provider's decision. Routing does not guarantee no ID request.
- The available list can change. A Test-mode list is not a live country-availability test.
Railbed's adult AI payment verification should therefore be described as provider-dependent. Do not promise a universal outcome from a routing label.
What affects the buyer's payment path?
The source documents support several concrete factors that determine eligibility and routing. They do not provide a reliable public formula for predicting who will be asked for ID.
Buyer location
A provider must be available to that buyer. A payment option shown in one market does not prove the same option works elsewhere. Review the countries that produce your actual paying customers rather than a worldwide marketing claim.
Checkout amount
Provider minimums matter. A very small purchase can have fewer eligible routes or fall below the available card methods' minimums. Check current requirements for the actual buyer market and payment flow. That is a product-design consideration, not a reason to manipulate transactions to avoid checks.
Checkout currency
Railbed documents checkout currencies separately from USDC settlement. Currency support and provider availability need to be assessed for the actual sale, not inferred from the merchant's preferred bank currency.
Provider availability and requirements
The eligible list can change over time. The provider also controls its payment page and verification process. Keep product copy accurate even when a specific provider is unavailable.
The separate access obligations of your service
Payment eligibility and content-access law are different. A service can have a functional card checkout while still needing age assurance before exposing adult material. Treat that as an access-control responsibility, not a marketing footnote.
Improve completion without evading checks
Explain the handoff before it happens
Tell customers that payment is completed through a card provider and that verification can be required. Use neutral language. Avoid frightening legal copy where a short factual sentence is enough.
A suggested explanation is: You will complete card payment with a payment provider, which may ask you to verify your identity. This is example product wording, not a claim that it satisfies every disclosure requirement.
Keep the product promise visible: the pack, pass or unlock the customer is buying should remain understandable throughout the transition.
Keep the original purchase context
Railbed's buyer-experience guide explains the two-tab flow. The provider's final page does not control your original checkout's return behavior.
Tell customers to keep the original tab open. If they close it, the app should still recover verified purchases through the server. Closing a page is not the same as canceling money already sent.
Ask only for details needed for the stated purpose
Do not collect extra identity documents in your own support system merely because another provider might ask for them. The provider should conduct its own required checks through its appropriate process.
For your own order form, distinguish information needed to deliver access from information needed for a legally justified check. Collecting more data creates more material to secure and explain.
Make retries understandable
A buyer whose card is declined can be shown a legitimate alternative route where the provider arrangement permits it. Railbed documents a Choose another way to pay option.
Before asking for a fresh payment, inspect whether the original order is already paid, pending or held. A customer who thinks they were charged needs investigation, not a second pay button with no explanation.
Keep required checks intact
Do not split one purchase into smaller transactions to stay below identity or reporting thresholds. Railbed's acceptable-use policy explicitly prohibits this. Do not suggest false location information, another person's identity or misleading product descriptions.
Reducing confusion is a checkout improvement. Defeating a required check is not.
Use checkout messages that answer the next question
These are suggested interface messages, not guarantees or legal templates. Adapt them to the actual state your integration has verified.
| Where the buyer is | Suggested message | Why it helps |
|---|---|---|
| Before leaving the app | Complete card payment with our payment provider. The provider may ask you to verify your identity. | Explains who asks for information before the handoff |
| Provider page has opened | Keep this checkout open. Return here after payment to see its status. | Makes the separate tab understandable |
| Payment is still unconfirmed | We are waiting for payment confirmation. If you believe you paid, contact support with your order reference before trying again. | Reduces confusion without falsely declaring a decline |
| Payment needs review | This payment needs review. We will check it before asking you to take another payment step. | Avoids telling a buyer to top up or pay again blindly |
| Purchase is confirmed and delivered | Payment confirmed. Your purchased credits or access are available in your account. | Reports delivery only after it actually happened |
For an adult AI app, keep payment messages separate from roleplay. A fictional companion should not be the only source of information about identity collection, real-money purchases or customer support.
Do not add a second ID hurdle after verified payment
Once Railbed confirms Paid, use the normal saved-order and delivery checks. Do not ask the buyer to send identity documents to your team merely because an article mentioned possible provider verification.
If your own lawful account or content-access review remains necessary, give it a separate purpose, owner and privacy process. Payment confirmation is not a reason to collect unnecessary documents, and a payment-provider check is not an automatic substitute for legally required age assurance.
Age assurance is not the same as buyer identity collection
Ofcom's UK guidance states that certain generative AI tools publishing pornography fall within the relevant regime. For services in scope, highly effective age assurance must prevent children from normally encountering the material.
Its guidance lists methods capable of being highly effective when properly implemented, including photo ID matching, facial age estimation, digital identity services, certain credit-card checks and other methods. That is not a blanket endorsement of every implementation.
The same guidance says self-declared age and online payments that do not require the user to be an adult are not highly effective. It also states that pornographic material should not be visible before or during the age check.
For a founder, the distinction is practical:
- A date-of-birth field records what a user says.
- A payment-provider identity check serves that provider's process.
- A content-access decision must satisfy the applicable legal standard.
Railbed's reusable-checkout documentation explicitly says its date-of-birth field is not an ID check. Do not relabel it verified age in your product or compliance records.
This guide does not provide a country-by-country legal opinion. Have qualified advice establish which duties apply to your service, then implement the access controls deliberately.
Treat the age decision as a separate product permission
An app can distinguish permission to enter adult-content areas from permission to spend purchased credits. This is a suggested design boundary, not a claim that every app uses the same architecture.
Keep a record of the required access decision without copying identity documents into the credit ledger. Apply the gate wherever protected material can appear, including generated previews and shared galleries—not only on the final generation button. Ofcom's cited guidance says pornographic material must not be visible before or during the age check.
Review who receives age-assurance information and how long it is kept. Your support team should be able to explain the access requirement without seeing a customer's private prompts or full identity documents.
Privacy expectations need accurate language
Adult AI users can be concerned about discretion. Address that concern without making promises your payment chain cannot support.
Card payment involves financial records. A customer paying by card should not be told the transaction is anonymous. Likewise, do not promise a particular statement descriptor unless the responsible provider has confirmed the actual descriptor for the relevant flow.
Explain the division of responsibility: your app stores account and purchase records; the card provider handles the information it collects on its payment page; any age-assurance provider has its own role. Your privacy documentation should reflect the real arrangement.
Operational safeguards to consider include:
- Keeping sensitive documents out of ordinary chat and email.
- Restricting staff access to personal information by role.
- Avoiding explicit prompts or generated content in routine payment logs.
- Linking orders to internal account references rather than unnecessary intimate details.
- Defining retention, deletion and incident handling with appropriate advice.
These are recommended safeguards, not claims of a particular certification or automatic compliance.
Distinguish payment states before diagnosing abandonment
Not every unfinished checkout is a card decline. Railbed says live card declines occur on the provider page and are not directly reported as a decline event. The merchant dashboard can still show Open or In progress.
Similarly, a held payment indicates an exception that needs review, not a completed purchase ready for automatic delivery. An expired payment can later become Paid or Held if funds arrive late.
| Observed state | Responsible next step | Wrong conclusion to avoid |
|---|---|---|
| Buyer reached provider but did not return | Inspect actual payment state | Every absent return means a decline |
| Payment is pending | Show a waiting state and check confirmation | Credits should already be granted |
| Payment needs a decision | Review the exception | Tell the buyer to pay the same order again immediately |
| Payment is Paid but app access is missing | Investigate entitlement delivery | The customer must retry payment |
| Net settlement is not yet reported | Wait for and reconcile the settlement detail | Substitute the gross order amount as received cash |
This separation helps support answer the real problem without creating duplicate payments.
Measure what your systems can actually observe
A merchant does not necessarily receive the provider's internal verification outcomes. Do not invent an ID-check rate by treating every abandoned provider visit as an ID refusal.
Start with observable events: checkout started, provider handoff, confirmed payment, entitlement delivered and support request. Add verification-specific reporting only where you have legitimate, reliable data for that event.
Compare matched country, device and purchase cohorts in 2026. If a new flow is used for larger packs or different countries, a raw before-and-after rate does not isolate the payment design.
Useful questions include:
- Where does the last confirmed event occur?
- Which buyers report confusion about the provider?
- Do successful payments consistently grant access?
- Are duplicate purchases concentrated around pending states?
- Are support requests about identity, price, navigation or delivery?
Use observed provider outcomes and customer reports rather than assigning every unfinished checkout to an ID check. Mark unknown causes as unknown so payment changes address evidence rather than assumptions.
Compare provider models on verification, not promises
| Arrangement | Best for | Verification question to ask | Tradeoff |
|---|---|---|---|
| Railbed card checkout with USDC settlement | Teams selling customer-initiated purchases and managing wallet funds | What does the actual buyer flow require in our markets? | Card-provider identity checks still apply; no automatic renewals |
| Conventional adult merchant account | Businesses seeking eligible conventional card and recurring-billing services | Which merchant checks and buyer challenges apply to this product? | Underwriting and contract terms need product-specific assessment |
| Direct wallet payment | Buyers already prepared to pay with crypto | What separate age, account and legal checks must we perform? | Removing a card flow does not remove content-access responsibilities |
For established merchants, ask for a practical demonstration of the relevant buyer journey. A no-underwriting claim answers a merchant question. It does not answer a buyer-ID question.
Railbed is our first choice for adult AI card checkout with USDC settlement. Its routing gives buyers eligible payment options while keeping verification decisions with the card provider; it does not promise an ID-free checkout.
FAQ
Will every adult AI buyer be asked for ID?
Not every transaction has the same identity requirements. In Railbed's card flow, the chosen card provider decides which checks are required.
Does no merchant underwriting mean no customer ID checks?
No. Merchant onboarding and buyer verification are separate processes. A provider can ask a buyer for verification even when merchant signup is minimal.
Does Smart Routing guarantee that a card will be approved?
No. Railbed's documentation describes Best match as a recommendation, not an approval guarantee. The provider can still decline the card or require checks.
Does paying by card prove a buyer is old enough for adult content?
A generic card payment is not universal proof of legally sufficient age assurance. Assess the method and applicable content-access duties separately.
Is a date-of-birth field an identity check?
Railbed's checkout documentation says its date-of-birth field records what the buyer states and is not an ID check. Do not label self-declaration as verified age.
Can I split a payment to avoid verification?
Do not split purchases to evade identity checks or reporting thresholds. Railbed's acceptable-use policy explicitly prohibits that behavior.
Can customers pay anonymously by card?
Do not promise anonymous card payment. The payment provider and financial institutions can collect information and maintain transaction records.
Does a successful Test checkout prove buyers will not need ID?
No. Test mode simulates the journey and does not establish live eligibility, approval or verification requirements for real buyers.
One last thing: promise clarity, not anonymity
You can control your explanation, order records and delivery process. You cannot honestly promise that another provider will never ask for identification.
For an adult AI app processing more than $50,000 monthly, evaluate the buyer flow with the same care as settlement. A payment arrangement is useful only when the customer understands the purchase and the business can fulfill it reliably.
Sources and scope
Reviewed 7 November 2026. Product statements reflect the cited Railbed documentation; legal discussion is limited to the public UK guidance and is not a global compliance opinion.
- Ofcom: age checks to protect children online, published 16 January 2025; methods, scope and limits relevant to this 2026 guide.
- Stripe prohibited and restricted businesses, updated 22 September 2026; adult AI eligibility is separate from transaction authentication.